Martial Arts Insurance: What It Costs and What It Covers (2026)
Imagine it's a Tuesday, it's 10am, the pen is already in your hand, and you're about to sign the lease on your first gym space.
Then your landlord slides one more page across the table.
"I'll need proof of insurance with me listed as additional insured. A million in general liability, minimum."
You freeze. Additional what? A million dollars?
You're opening a BJJ academy. Nobody's jumping out of a plane. Every martial arts school owner hits this moment.
I'm a marketing guy, which means two things. You're not getting armbar tips from me, and you're not getting insurance advice either. A licensed agent gets the final word on your policy.
So I did the homework.
I read the rate sheets and program pages that martial arts insurance carriers publish, so every price and limit below comes from a carrier's own site, as of October 2026.
To keep the math honest, I'll run one made-up academy through the whole post: Arm Bar & Grill, 60 students at its busiest point of the year, one location, about $12,000 of mats and bags. (No food is served. I couldn't help myself.)
QUICK ANSWER
How Much Does Martial Arts Insurance Cost?
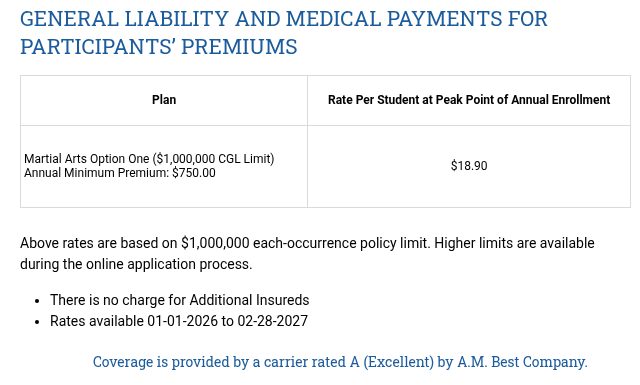
Two martial arts school programs publish their rates, K&K Insurance and Sadler Sports & Recreation, and their numbers match. Sadler lists $18.90 per student per year with a $750 minimum for $1 million in liability plus medical coverage for participants, as of October 2026.
That's about $1,134 a year for a 60-student school, before taxes and fees.
What Martial Arts Insurance Covers
Martial arts insurance is a bundle of policies that pays when someone gets hurt at your school or your stuff gets wrecked.
At a martial arts school, the claim you'll think about most is a student hurt in class. The policy decides who pays the doctor and who pays the lawyer.
Here's what each piece of the bundle does:
Coverage | What it pays for |
General liability | Injury or damage to other people, plus your legal defense |
Participant medical | Students' medical bills after their own health insurance |
Professional liability | Claims that your instruction caused the harm |
Equipment and contents | Mats, bags, and gear lost to theft, fire, or vandalism |
Workers' compensation | Injuries to your employees |
The types of gym insurance most gyms carry map onto this list.
The difference is packaging. Martial arts programs tend to bundle participant medical and professional liability into the liability policy.
General liability
This is the one your landlord asks about.
It covers the parent who trips over a gi bag in the lobby, and the legal bill when someone claims you're responsible.
Limits come as two numbers, per occurrence and aggregate. The landlord section below explains the difference.
Published examples, as of October 2026:
- Philadelphia Insurance's martial arts studio program lists $1 million per occurrence and $3 million aggregate for general and professional liability, with a zero deductible on general liability.
- Sadler's school program lists $1 million per occurrence and a $5 million aggregate per owned location, with higher limits available when you apply.
Medical coverage for participants
This one pays a student's medical bills after an injury in class, whether or not anyone sues.
Read the fine print on order of payment.
Sadler's participant medical coverage pays up to $150,000, dental included, with a $250 deductible per claim.
It's also excess coverage, so it responds only after the student's own health insurance (family plan included) has paid what it's going to pay.
Parents will ask about this part, so know it before they do.
Professional liability
Professional liability covers the claim that your teaching was the problem: you pushed a student too hard, or promoted them before they were ready.
K&K, Sadler, and Philadelphia Insurance all bundle it in:
- K&K lists professional liability inside its general liability coverage.
- Sadler includes $1 million of it.
- Philadelphia Insurance writes general and professional liability together.
Equipment and workers' comp
Equipment and contents coverage is usually an add-on, and it's worth pricing at the same time you're buying gym equipment.
Sadler prices it as a share of replacement cost: 3% of replacement value for up to $10,000 of gear, and 2.6% for more than that.
Sadler also warns that you have to insure the full replacement value. Insure less, and you face a co-insurance penalty when you claim.
For Arm Bar & Grill: its $12,000 of mats and bags × 2.6% = $312 a year, with a $1,000 deductible.
Workers' comp is the policy people forget until they hire. ERGO NEXT's martial arts instructor page notes that most states require workers' compensation if you have employees.
What Martial Arts Insurance Costs in 2026
On the published school programs, $1 million of liability plus participant medical costs $18.90 per student a year, counted at your peak enrollment, with a $750 annual minimum.
That's Sadler's rate sheet, and K&K's enrollment brochure lists the same $18.90 and $750 minimum. Sadler's rates run from January 1, 2026, through February 28, 2027.
Beyond those two, most martial arts insurers don't publish prices. You fill out an application, and they quote you.
Here's what that works out to at a few school sizes:
Students at peak | Annual premium |
25 | $750 (minimum) |
50 | $945 |
75 | $1,418 |
100 | $1,890 |
150 | $2,835 |
200 | $3,780 |
Source: Sadler Sports & Recreation martial arts school rates ($1 million limit), October 27, 2026. Before taxes, fees, and optional coverage.
Below about 40 students, you're paying the minimum.
For Arm Bar & Grill: its 60 students × $18.90 = $1,134, plus $312 for equipment. Call it $1,446 a year before taxes and fees, or a bit over $120 a month.
Wondering whether $1,446 fits? The guide to what BJJ gym owners make has the revenue side, and the breakdown of the cost of opening a martial arts school has the rest of the startup budget.
That's one program at one limit. A carrier that quotes on application can land above or below it, and higher limits cost more.
You can see that last part on Sadler's individual instructor policy, which publishes every tier.
A traditional martial arts instructor pays $375 a year for a $1 million limit and $553 for $2 million, plus a $20 group fee. That's $178 more for the higher limit.
School programs step up too. K&K's enrollment brochure lists a $1,125 minimum premium at the $2 million option, up from $750 at $1 million.
What about the big general insurers? Fit Small Business pulled a quote from The Hartford for a three-employee fitness center in Georgia: $41.83 a month for general liability at $1 million per occurrence and $2 million aggregate.
That quote is for a fitness center and covers general liability only, with no participant medical, so treat it as a rough floor.
What moves your premium
Student count and limits are the big two, and both are covered above. The rest come from what you teach and what you add on.
A few things the published programs charge extra for:
- Side activities for non-members. Sadler's optional "Subsidiary Activities" coverage for non-registered members costs $14.50 per participant. Sadler says it covers yoga and exercise, meetings and seminars, floor tumbling, theater, basketball, volleyball, and other activities.
- Abuse and molestation coverage. Sadler offers $1 million of liability at $2.10 per participant, and that limit is part of your general liability limit, not added on top. The other option is $100 flat for $100,000 of defense-cost reimbursement.
- Hosted tournaments. K&K sells hosted tournament coverage as an optional add-on (more on that below).
BJJ, MMA, Karate, and Boxing: What Changes by Style
Your style decides whether a program will write your school at all, and which events it covers.
K&K and Sadler publish the same eligibility list, and it's specific. How the list sorts out:
Style | Eligible? | Competitions |
BJJ, judo, karate, taekwondo | Yes | Not excluded (supervision and reporting terms apply) |
Kickboxing with sparring | Yes | Not excluded (supervision and reporting terms apply) |
MMA, Muay Thai, kali/escrima | Training only | Excluded |
Contact boxing, wrestling | No | Not offered |
Source: K&K Insurance and Sadler Sports & Recreation martial arts school program pages, October 27, 2026.
Other carriers draw the lines in other places. Markel's martial arts page lists 18 styles, from aikido to Wado-ryu, and Brazilian Jiu-Jitsu isn't on it.
Markel may still write a BJJ school. Ask before you assume.
BJJ schools
The "gentle art," famous for strangling people politely, is hardest on elbows.
A study of eight Hawaii BJJ tournaments from 2005 to 2011 found 9.2 injuries per 1,000 match exposures. Orthopedic injuries made up 78% of them, the elbow was the joint hurt most often, and the armbar was the most common cause.
That's the injury your participant medical limit and deductible will meet first.
For a BJJ school, the practical questions are:
- Does participant medical coverage pay enough for an elbow or knee injury after the student's health insurance?
- Are open mats with visitors from other academies covered? (See below.)
- Does the policy cover students at outside tournaments, or only events you run?
MMA gyms
MMA is where eligibility gets strict.
K&K covers MMA training only. Competitions are out, whether you host or your members compete, and the tournaments section below has the details.
K&K also doesn't cover managing or promoting fighters, amateur or pro.
If you run a fight team, that's a separate conversation with an agent who writes combat sports events. Ask it before the first amateur bout gets booked, and ideally while you're still planning how to open a martial arts school.
Karate and taekwondo schools
Most martial arts programs will write a traditional striking school, and these are the schools most likely to run their own tournaments.
Two questions are worth asking up front.
Does your policy cover weapons training if you teach kobudo? And does it cover board and brick breaking at belt tests?
Sadler's individual instructor policy lists sharpened or bladed weapons and projectile weapons under its exclusions. The school program pages I read didn't address weapons training or board breaking at all, so get the answer in writing.
Boxing gyms
If you landed here searching for boxing gym insurance, this part's for you.
Contact boxing isn't eligible on K&K or Sadler's martial arts programs. Non-contact fitness boxing is. A boxing gym with sparring needs a program that writes boxing specifically.
Tournaments: What Your Policy Covers and What It Doesn't
Most schools run into tournament coverage twice: the first time a student registers for an outside event, and the first time you want to host one.
When your students compete somewhere else
Whether your policy follows students to another gym's mats depends on the policy.
K&K's program is a useful example. It covers activities with registered participants under your direct supervision or organized by you, as long as they've been reported, paid for, and approved.
That can include approved off-site locations.
The styles where competitions are excluded (MMA, Muay Thai, kali/escrima, and a few others) stay excluded no matter who's supervising.
For MMA, K&K's FAQ rules out any involvement in tournaments, competitions, or events, whether you're hosting or your members are competing.
Does your policy exclude competitions for your style? (MMA, Muay Thai, kali/escrima on the K&K and Sadler programs)
Not covered, no matter who's supervising. Talk to an agent who writes combat sports events.
Is it under your direct supervision or organized by you, and reported, paid for, and approved?
Possibly covered on terms like K&K's. Get it confirmed in writing before the event.
Your student registered on their own and went without you.
Assume they rely on the organizer's terms and their own medical insurance. Ask your agent.
Every policy words this differently. This is the order of questions to ask, not a coverage answer.
The organizer's side matters just as much.
Some event waivers put medical costs on the athlete in plain words. Warrior Cage Grappling's waiver, for one, requires competitors to carry their own primary medical insurance as a condition of registering.
I couldn't confirm what the big federations require, so I won't guess. Have students read the organizer's waiver and membership rules before they register, and ask your agent the plain question: does my policy cover my students at an outside tournament, and do I have to be there supervising?
ASK YOUR AGENT
Does my policy cover my students at an outside tournament, and do I have to be there supervising?
Then have students read the organizer's waiver and membership rules before they register. Some events require competitors to carry their own primary medical insurance.
One more wrinkle. K&K's FAQ says its program doesn't cover transporting students to classes, tournaments, or exhibitions.
If you're driving the team van to an event, that's a separate policy.
If you're still deciding whether a team is worth it, start with investing in a competition team.
When you host
Hosting is its own coverage.
K&K sells hosted tournament coverage as an optional add-on. It defines a hosted tournament as one you organize and run that includes participants who aren't active members of your school, and the event has to be seven days or shorter.
If you're planning one, the in-house tournament guide covers the rest of the logistics, and martial arts tournament software can take registration and brackets off your plate.
Price the coverage before you print the flyer.
Open Mats, Drop-ins, and Seminars
Open mats are great for a community and awkward for a policy. Many programs are written around enrolled students.
K&K's online application is off the table if your open gym time isn't limited to members, so you'd apply on paper.
Sadler's per-participant coverage for non-registered members is sold as "Subsidiary Activities" (yoga, seminars, floor tumbling, and the like), not as open-mat coverage.
Whether that, or K&K's coverage for non-registered members, covers a visitor rolling at your open mat is a question for your agent.
The visitors to think about:
- A blue belt from across town at your Friday BJJ open mat
- Twenty students who follow a visiting black belt to a weekend seminar
- A member's friend on a free trial class
Ask your agent how each one is covered, by name. If the answer is "they're not," add the coverage or stop letting non-members on the mat until you do.
Kids Programs and Parents
Parents at a kids program trial class tend to ask one question first: what happens if my kid gets hurt?
Now you can answer: participant medical pays after their family health insurance, up to your policy's limit.
Two things to check for a kids program:
- Abuse and molestation coverage. Philadelphia Insurance lists $100,000 per occurrence for sexual abuse liability, and Sadler offers a $1 million option that shares your general liability limit. If you teach children, this belongs on your list.
- A signed waiver for every child. The policy is still what pays. You just want the waiver on file before the first class.
This is where your software helps. In Gymdesk, a parent signs the waiver during online signup, with a guardian signature for minors.
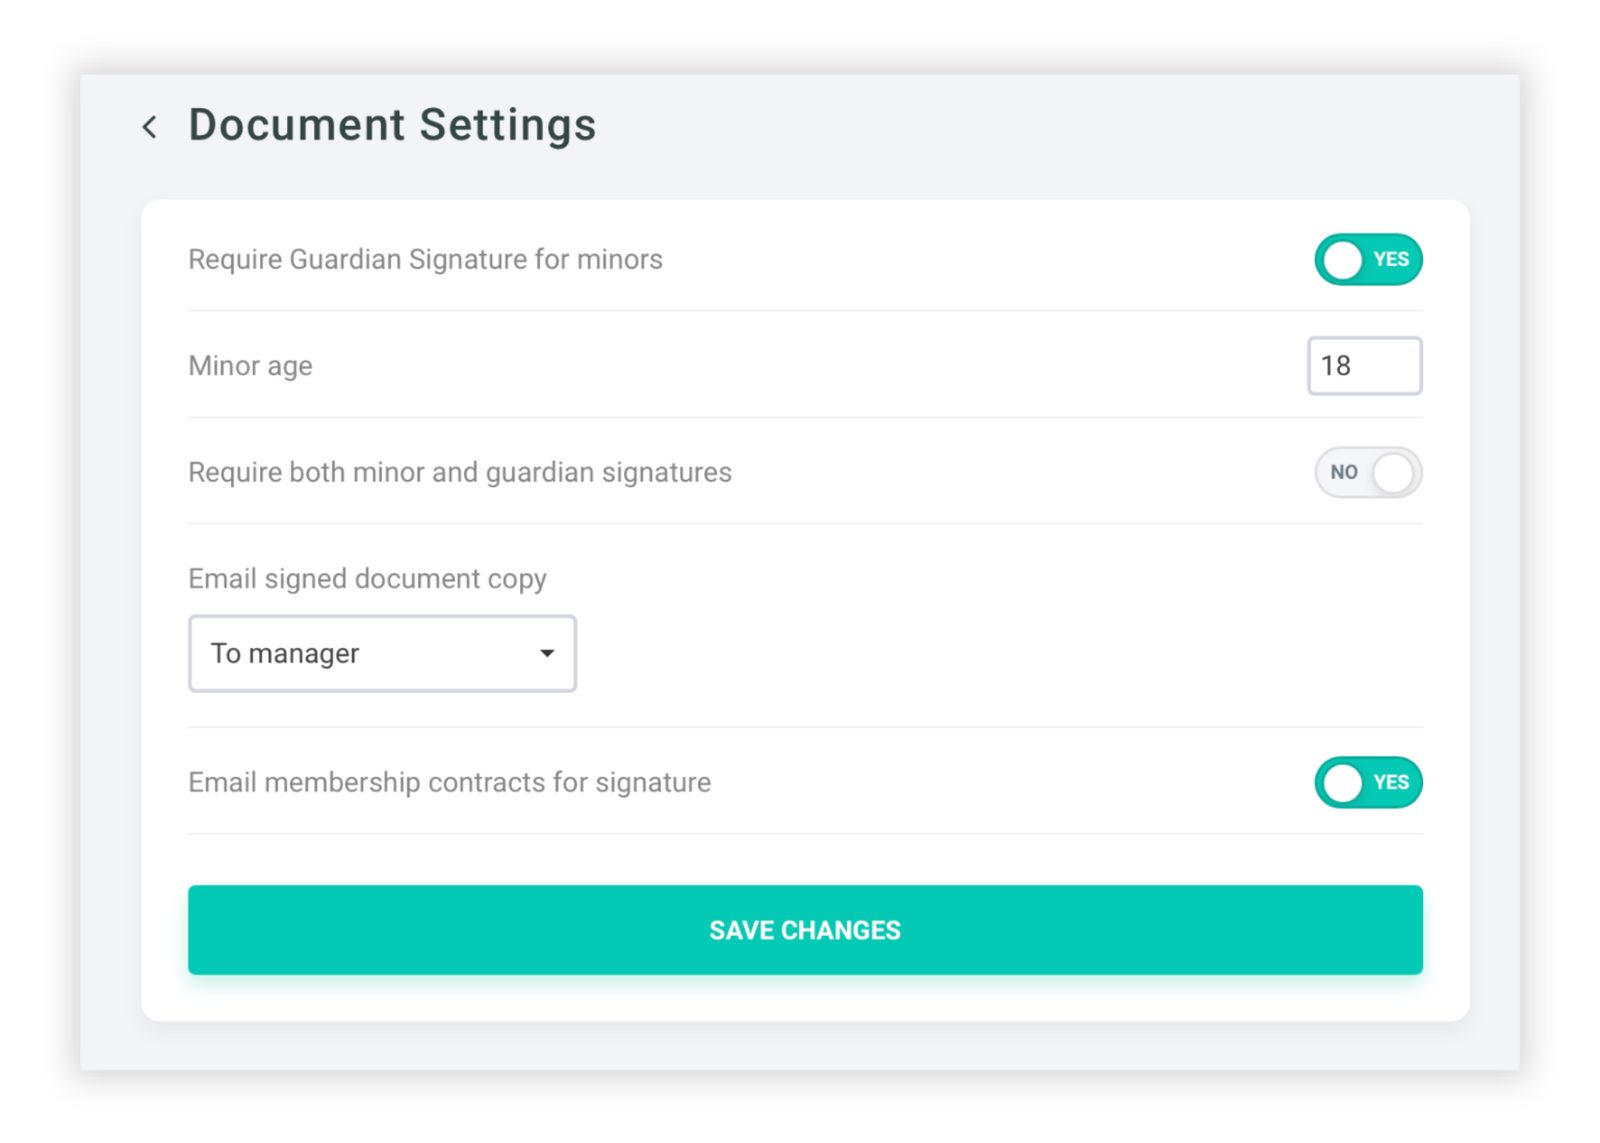
The member profile holds emergency contacts and medical notes, so the front desk has the parent's number before anyone needs it.
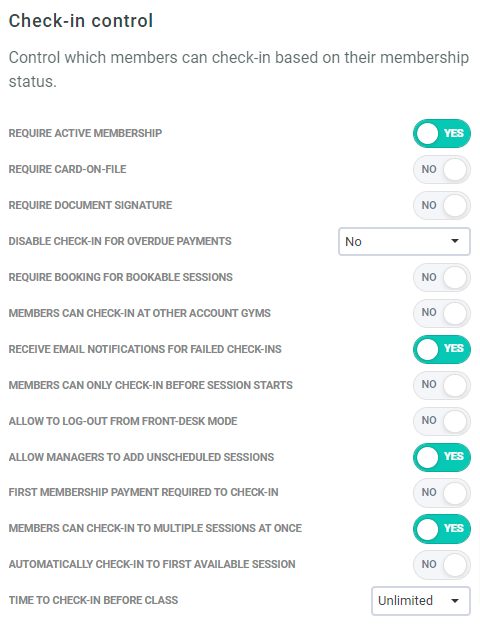
You can also set check-in to turn away anyone with an unsigned document. That closes the gap with the drop-in who "definitely signed last time."
What Your Landlord Needs to See
Your landlord wants to know who pays if someone gets hurt in your space. What settles it is a certificate of insurance that names them as additional insured, with limits that match the lease.
Certificate of insurance
A certificate of insurance (COI) is a one-page summary of your coverage. It shows:
- Policy types and limits
- Effective dates
- The insurance company
- The certificate holder (your landlord)
- Additional insured status
On programs like K&K's, the certificate is your proof of coverage. K&K publishes a certificate request form, and ERGO NEXT lets policyholders create certificates themselves.
Additional insured
"Additional insured" means your landlord is added to your liability policy as a protected party. If someone gets hurt and sues both you and the landlord, your policy defends the landlord too.
It's usually cheap or free.
Sadler lists no charge for additional insureds, and ERGO NEXT says adding one is free.
Ask for the endorsement when you buy the policy. A certificate without it tends to get bounced back the week you're trying to open.
Per occurrence vs aggregate
A lease that asks for $1 million per occurrence and $2 million aggregate is asking about two different ceilings.
Claim 3 that year: the aggregate is spent, so the policy pays nothing more until it renews.
The per-occurrence limit is the most the policy pays for one incident. The aggregate is the most it pays for every claim in the policy year.
So that policy pays up to $1 million for any single claim. Two big claims in one year and the aggregate is spent. That's why a landlord might ask about the aggregate, and why a $3 million or $5 million aggregate, like the programs above, gives you more room.
BEFORE YOU SIGN THE LEASE
Ask for the additional insured endorsement when you buy the policy, and check that your per-occurrence and aggregate limits match what the lease asks for. A certificate without the endorsement tends to get bounced back the week you're trying to open.
Martial Arts Insurance Companies to Compare
A few carriers write programs built for martial arts schools. Others write general fitness or small business coverage that may or may not fit how you train.
What each one publishes, as of October 2026:
Provider | What they sell | Published price |
K&K Insurance | Martial arts school program | Per-student rates in its enrollment brochure, including $18.90 and a $750 minimum |
Sadler Sports & Recreation | School program and instructor policy | $18.90 per student, $750 minimum |
Philadelphia Insurance (PHLY) | Martial arts studio program | Not published |
Markel | Liability and property for listed styles | Not published |
Lockton Affinity Fitness | Instructor professional liability | From $105 a year |
ERGO NEXT | Instructor liability, property, and workers' comp | No clear published price |
Sources: each provider's martial arts page, plus K&K's enrollment brochure linked from its page, October 2026.
Some of these programs share forms and rates.
K&K and Sadler use matching application form numbers and publish the same rates, and Markel's martial arts page sends its agent link to K&K's site.
So when you collect three quotes, make sure they come from three different underlying programs.
If you have a contract coach teaching your no-gi class, a policy in their own name is worth asking about. That's what the last two rows are: individual instructor policies.
Lockton Affinity Fitness starts at $105 a year for an employed instructor and $117 for a self-employed one, before taxes and fees. ERGO NEXT says its instructor coverage requires a certification or a four-year degree in a health and fitness field.
What martial arts group insurance means
For two of the programs above, "group insurance" means you buy through a group that holds a master policy.
K&K's school program is sold through the Sports, Leisure and Entertainment Risk Purchasing Group. K&K's own FAQ explains that when you apply, you join that group, and you get a certificate of insurance as your proof of coverage.
Your limits are your own.
K&K says there are no shared limits with other members, so another school's bad year doesn't eat your coverage. Sadler's instructor policy charges a $20 fee for the same kind of group membership.
How to compare quotes
Get at least three quotes from different underlying programs, and line them up on the same limits.
Compare these, in this order:
- What's excluded. Competitions, non-members, weapons, transport, and styles like MMA are where policies differ most.
- How participant medical pays. Excess or primary, the maximum, and the deductible.
- The limits. Per occurrence and aggregate, and what your lease requires.
- The price. Last, once the first three match.
If cash flow is tight, ask about installments. Philadelphia Insurance offers installment plans once your premium reaches $2,000 a year, and Markel's martial arts page mentions installment plans too.
A cheap policy that excludes your Friday open mat is expensive on the Friday it matters.
How to Lower Your Martial Arts Insurance Costs
Sadly, nobody hands out a promo code. Most of the savings come from buying the right thing once.
What actually brings the number down:
- Start with the students you have. K&K lets you add students at any time with its supplemental form, so update it as you grow.
- Insure equipment at full replacement value. Underinsuring triggers a co-insurance penalty, so the cheap option costs you at claim time.
- Ask about safety programs. Philadelphia Insurance pitches industry-specific safety programs as a way to keep costs down. Sadler publishes free risk management material, including sample adult and minor waivers and a concussion awareness program, and the guide to gym safety best practices covers the basics.
- Match limits to your lease. Buy what the lease and your risk require, then stop.
- Keep a clean record. Fewer claims make for an easier renewal conversation.
Common Insurance Mistakes Martial Arts Gym Owners Make
Most of these only show up once you file a claim.
The ones to avoid:
- Relying on waivers alone. A signed liability waiver is the first thing anyone asks for when a claim comes in, and it can still be challenged in court. You need the policy behind it.
- Assuming homeowner's insurance covers a garage dojo. The Insurance Information Institute notes a typical homeowners policy covers only $2,500 of business equipment, and liability endorsements are usually limited to businesses with few visitors. Call your insurer before the first student shows up.
- Forgetting the additional insured endorsement. Request it when you buy the policy.
- Letting coverage lapse in a slow month. An injury during a gap is yours to pay.
- Adding programs without telling your insurer. K&K, for example, sends schools that offer anything besides martial arts to a paper application. New programs can change what you're eligible for.
- Skipping equipment coverage. Liability coverage won't pay to replace a flooded mat room.
Get Three Quotes Before You Sign the Lease
Back to that Tuesday and the pen in your hand.
A school the size of Arm Bar & Grill runs about $1,446 a year on Sadler's published rates, before taxes and fees.
Your next steps:
- Get at least three quotes at the same limits: one from K&K or Sadler, and at least two from carriers that quote on application.
- Ask each one about competitions, open mats, and kids coverage by name.
- Add your landlord as additional insured when you buy.
- Put your renewal date somewhere you'll see it.
Then sign the lease.
FOR MARTIAL ARTS SCHOOLS
The policy pays, but a signed waiver is the first thing anyone asks for when a claim comes in. Gymdesk collects waivers at online signup, with guardian signatures for minors, and can turn away a check-in with an unsigned document.
- No credit card required
- No contracts
- Cancel anytime
Gym management software that frees up your time and helps you grow.
Simplified billing, enrollment, student management, and marketing features that help you grow your gym or martial arts school.

FAQ
Martial Arts Insurance FAQs
The short answers:

Sean has spent the last decade creating content that helps businesses—small and not so small—grow smarter to allow operators to do more of what they love. You know, the fun stuff.
From shipping and international logistics to web development and marketing, he's done the work (not just the words) to scale retail and service businesses efficiently.
You can find his work at Sendle, Shogun, The Retail Exec, Gymdesk, and more.